# LayerBank

LayerBank — the Unified Cross-Chain Money Market

LayerBank is building the next generation of decentralized finance: a truly omni-chain lending protocol that unifies liquidity across 17+ EVM/non-EVM networks. Our mission is simple — make capital efficient, borderless, and composable.

Whether you are a lender seeking optimized yields, a borrower unlocking leverage, or a protocol integrating cross-chain liquidity, LayerBank provides the infrastructure to power your strategy.

#### **Why LayerBank?**

* **Omni-Chain First:** Seamlessly lend, borrow, and loop across multiple chains in a single UX.
* **Capital Efficiency:** Automated looping vaults and eMode risk frameworks amplify your yields safely.
* **Real-World Yield Access:** Integrated RWA markets bring sustainable, off-chain income on-chain.
* **Open & Permissionless:** LayerBank is governed by $ULAB holders and designed for builders and users alike.

LayerBank’s documentation is your guide to understanding how it all works — from architecture to tokenomics — and how to get the most out of the unified money market.


# Lending

Lending & Borrowing on LayerBank

## **How LayerBank Works**

LayerBank is a decentralized money market built on an over-collateralized lending model, allowing users to:

* **Supply** assets and earn interest
* **Borrow** against their collateral
* **(Soon) Earn $ULAB rewards** for participating in the market

***

### **lTokens (Interest-Bearing Tokens)**

When users supply assets to LayerBank, they receive lTokens representing their share of the pool.

* **Initial Exchange Rate:** lTokens start at 1:1 with the underlying asset (e.g., 1 USDC = 1 lUSDC).
* **Accrued Interest:** Over time, the exchange rate increases as interest accrues (e.g., 1 USDC = 1.03 lUSDC).
* **Redemption:** When withdrawing, users redeem lTokens for their share of the underlying asset plus accrued interest.

lTokens effectively track your position and the interest earned automatically.

***

### **Borrowing & Collateral**

To open a borrow position, users enable collateral on their supplied assets.

* **Borrow Limit:** Determined by the Max LTV (Loan-to-Value) of the collateral.
* **Interest Accrual:** Borrowed amounts grow over time according to the Borrow APR.
* **Example:**
  * Deposit 100 USDC → Receive lUSDC representing your deposit
  * Borrow 50 USDC → Owed amount grows as interest accrues
  * To close the position, repay the borrowed amount (plus interest) and withdraw remaining collateral

> **Risk Note:** If the collateral value drops and exceeds the Max LTV threshold, the position can be partially liquidated to maintain solvency.

***

### **Dynamic Interest Rate Model**

LayerBank operates in a fully on-chain, code-driven environment with no intermediaries.

* **Utilization-Based Rates:** Borrow/Supply APRs adjust automatically according to pool utilization.
* **Goal:** Keep liquidity healthy — higher rates at high utilization attract more suppliers and encourage debt repayment.
* **Result:** A self-balancing money market with optimized capital efficiency.

***

### **Key Benefits**

* **Trustless & Automated:** 100% smart contract based, no centralized custody
* **Capital Efficiency:** Borrow up to the Max LTV while keeping collateral secure
* **Transparent Yield:** lTokens make interest accrual transparent and verifiable on-chain


# Interests

## **Interest Rate Model**

Interest rates in LayerBank are dynamic and determined by a utilization-based interest rate curve.\
This ensures that lending markets remain balanced — incentivizing borrowing when liquidity is abundant and attracting deposits when liquidity is scarce.

***

### **Utilization Rate (U)**

Utilization measures how much of the pool's liquidity is currently borrowed:

<h3 align="center"><span class="math">U = \frac{\text{Borrowed}}{\text{Supplied}}</span></h3>

* **Low Utilization (U ↓)** → lower borrow rates, encouraging more borrowing.
* **High Utilization (U ↑)** → higher borrow rates, attracting more suppliers.

This feedback loop helps maintain an efficient capital market.

***

### **Borrower Interest Rate**

The Borrow APR is calculated using a double-slope interest rate model:

* **Below Optimal Utilization:** Borrow APR increases linearly at a slower slope (Slope 1).
* **Above Optimal Utilization:** Borrow APR rises more steeply (Slope 2) to quickly restore liquidity balance.

$$
R =
\begin{cases}
Slope\_1 \times U & \text{if } U \leq U\_{optimal} \\
Slope\_1 \times U\_{optimal} + Slope\_2 \times (U - U\_{optimal}) & \text{if } U > U\_{optimal}
\end{cases}
$$

* **Optimal Utilization (U\_optimal):** Target utilization level set by the protocol.
* **Slope 1 / Slope 2:** Parameters defining the interest rate curve’s sensitivity.

> **Example:**
>
> * Slope 1 = 4%, Optimal U = 80%
> * If U = 60% → Borrow APR ≈ 3.0%
> * If U = 90% → Borrow APR increases faster, protecting pool liquidity.

Borrow rates are recalculated continuously and may change at any time based on pool activity and DAO governance parameters.

***

### **Supplier Interest Rate**

Supplier (Lender) APR is derived from Borrow APR and Utilization:

$$
Supply\ APR = Borrow\ APR \times U \times (1 - Reserve\ Factor)
$$

* **Reserve Factor:** Portion of borrower interest allocated to the protocol treasury.
* **Effect:** As utilization rises, supplier APR increases, incentivizing more liquidity deposits.

***

### **Key Takeaways**

* **Dynamic Market:** Interest rates adapt in real time to market demand.
* **Capital Efficiency:** Keeps pools near optimal utilization, balancing supply & demand.
* **Incentive Alignment:** Higher rates at high U attract more suppliers, lower rates at low U attract more borrowers.
* **DAO Governance:** Parameters (Optimal U, Slopes, Reserve Factor) can be adjusted by governance to respond to market conditions.


# Collateral & Liquidation

When borrowing on LayerBank, the value of your collateral determines how much you can borrow and whether your position is safe.\
If your **borrowed value** grows too close to your collateral value (due to price drops or interest accrual), your position becomes at risk of **liquidation**.

***

### **Max LTV (Loan-to-Value)**

**Max LTV** is the maximum percentage of your collateral’s value that can be borrowed.

$$
Max\ LTV = \frac{\text{Borrow Limit}}{\text{Collateral Value}}
$$

**Example:**\
If the Max LTV for USDC is **80%**, and you supply **100 USDC**, you can borrow up to **80 USDC**.

***

### **Borrow Limit Calculation**

If you have multiple collaterals, your total **Borrow Limit** is determined by the **weighted average** of all supplied assets and their Max LTVs:

$$
Borrow\ Limit = \sum\_i (Collateral\_i \times Price\_i \times MaxLTV\_i)
$$

This ensures a diversified portfolio reflects an appropriate combined risk level.

***

### **Health Factor (HF)**

Your position safety is measured by **Health Factor**:

$$
HF = \frac{\text{Borrow Limit}}{\text{Borrowed Value}}
$$

* **HF > 1.0:** Safe (below max LTV).
* **HF = 1.0:** At risk (exactly at max LTV).
* **HF < 1.0:** Liquidation can be triggered.

***

### **Liquidation Process**

When HF < 1.0 (loan exceeds allowed LTV), a partial liquidation occurs:

1. Up to 50% of the borrower's debt is repaid by a liquidator.
2. The liquidator receives a 15% liquidation incentive (bonus collateral).
3. Remaining collateral is returned to the borrower.
4. Health Factor is restored above 1.0, making the position safe again.

***

### **Key Points**

* Liquidation is **partial** — only enough collateral is sold to bring HF back above 1.0.
* The liquidation incentive rewards third-party liquidators and keeps the protocol solvent.
* Maintaining a safe HF (e.g., >1.2) is recommended to avoid liquidation during volatile markets.

{% hint style="info" %}
Liquidations are executed automatically. In such events, LayerBank closes the borrower's position, reallocates the collateral value to the lending pool, and returns any residual assets to the borrower.
{% endhint %}


# APR

## **APR Overview**

APR (Annual Percentage Rate) in LayerBank represents the net yield or cost of your position.\
It updates in real time based on **market utilization**, interest models, and rewards.

***

### **Components**

* **Supply Base APR** – Interest earned for supplying assets. Rises as utilization increases.
* **Borrow Base APR** – Interest paid for borrowing assets. Increases with utilization.
* **Underlying Yield** – Yield from LSTs or RWA yield-bearing tokens (e.g., staking rewards, off-chain yield).
* **Incentive Rewards APR** – Temporary incentives or foundation rewards (e.g., liquidity mining campaigns).
* **Looped APY** – Effective yield when leverage is applied (includes both supply yield & borrow cost).
* **Future $ULAB Rewards** – $ULAB emissions will be added for suppliers and borrowers and reflected in Total APR.

***

### **Looped Net APY Formula**

$$
LoopedNetAPY=L×(U+Sb​+Sr​+I)−(L−1)×(Bb​−Br​)
$$

Where:

* **L** = leverage multiplier
* **U** = underlying yield (LST/RWA yield)
* **S\_b** = supply base APR
* **S\_r** = supply reward APR
* **B\_b** = borrow base APR
* **B\_r** = borrow reward APR

> **Tip:** Enable **E-Mode** to safely increase leverage (higher **L**) and boost yield within risk limits.

***

### **Notes**

* **Underlying Yield:** Some assets accrue yield on mainnet and must be unstaked/claimed manually.
* **Incentive Rewards:** May be time-limited and differ by chain or campaign. Always check active campaigns.
* **$ULAB Rewards:** Will be added soon, further boosting total APR.
* **Net APR can turn negative** if borrow costs exceed total yield — monitor utilization before applying leverage.


# Oracles Providers

LayerBank relies on multiple trusted oracle networks to price collateral assets across different chains.\
Accurate and decentralized pricing is critical for maintaining healthy lending markets and safe liquidations.

***

<figure><img src="https://342097286-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fvi5sScuffF7lLX6pHEo5%2Fuploads%2FA7hBd7gZrXvPURORbsaf%2Foracles_EO.png?alt=media&amp;token=9708cd6f-2b49-453f-8953-729fd0e18596" alt=""><figcaption></figcaption></figure>

### **eOracle**

* **Used on:** Linea, Scroll, Mode, zkLink Nova
* **Purpose:** Primary price feed provider for all collaterals and markets on these chains.
* **Reference:** [eOracle Blog](https://blog.eoracle.io/layerbank-integrates-eoracle-to-secure-its-200m-of-tvl/)

***

<figure><img src="https://342097286-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fvi5sScuffF7lLX6pHEo5%2Fuploads%2FS4VBwcL0UYaZXVDY6FG3%2Foracles_redstone.png?alt=media&amp;token=712a0d50-a9f8-4470-9774-3b1336698e94" alt=""><figcaption></figcaption></figure>

### **RedStone**

* **Used on:** Manta, Bsquared, BOB
* **Purpose:** Price feeds for collateral assets using RedStone Classic data.

\ <br>


# E-Mode (Efficiency Mode)

E-Mode, or Efficiency Mode, is a feature designed for correlated assets — enabling users to borrow with a higher Loan-to-Value (LTV) while maintaining safe risk parameters.\
This unlocks more capital efficiency for looping strategies and leveraged yield farming.

***

### **How E-Mode Works**

* **Correlated Assets:** E-Mode applies to assets that are highly correlated (e.g. mBTC/RBTC, stables).
* **Higher LTV:** Max LTV is raised (e.g. 70% → 85%) so users can borrow more against their collateral.
* **Lower Liquidation Risk:** Liquidation thresholds (LLTV) are slightly increased, but still maintain a safety buffer.
* **Use Case:** Ideal for looping, stablecoin farming, or delta-neutral strategies where the collateral and borrow asset prices move together.

***

### **E-Mode Parameters by Chain**

#### **Rootstock**

| **mBTC Correlated** | **LTV** | **LLTV** | **Collateral** | **Borrowable** | **Liquidation Penalty** |
| ------------------- | ------- | -------- | -------------- | -------------- | ----------------------- |
| **RBTC**            | 85%     | 90%      | ✅              | ✅              | **4%**                  |
| **mBTC**            | 85%     | 90%      | ✅              | ❌              | **4%**                  |

| **solvBTC Correlated** | **LTV** | **LLTV** | **Collateral** | **Borrowable** | **Liquidation Penalty** |
| ---------------------- | ------- | -------- | -------------- | -------------- | ----------------------- |
| **RBTC**               | 85%     | 90%      | ✅              | ✅              | **4%**                  |
| **solvBTC**            | 85%     | 90%      | ✅              | ❌              | **4%**                  |
| **xSolvBTC**           | 85%     | 90%      | ✅              | ❌              | **4%**                  |

| **Stables** | **LTV** | **LLTV** | **Collateral** | **Borrowable** | **Liquidation Penalty** |
| ----------- | ------- | -------- | -------------- | -------------- | ----------------------- |
| **USDT0**   | 88%     | 92%      | ✅              | ✅              | 4%                      |
| **USDC.e**  | 88%     | 92%      | ✅              | ✅              | 4%                      |

***

#### **Movement**

| **ETH Correlated** | **LTV** | **LLTV** | **Collateral** | **Borrowable** | **Liquidation Penalty** |
| ------------------ | ------- | -------- | -------------- | -------------- | ----------------------- |
| **WETH.e**         | 80%     | 85%      | ✅              | ✅              | 6%                      |
| **rsETH**          | 80%     | 85%      | ✅              | ✅              | 6%                      |
| **ezETH**          | 80%     | 85%      | ✅              | ✅              | 6%                      |

| **Stables** | **LTV** | **LLTV** | **Collateral** | **Borrowable** | **Liquidation Penalty** |
| ----------- | ------- | -------- | -------------- | -------------- | ----------------------- |
| **USDC.e**  | 92%     | 95%      | ✅              | ✅              | **6%**                  |
| **USDT.e**  | 92%     | 95%      | ✅              | ✅              | **6%**                  |
| **sUSDe**   | 92%     | 95%      | ✅              | ✅              | **6%**                  |

***

#### **Plume**

| **nALPHA-pUSD** | **LTV** | **LLTV** | **Collateral** | **Borrowable** | **Liquidation Penalty** |
| --------------- | ------- | -------- | -------------- | -------------- | ----------------------- |
| **nALPHA**      | 85%     | 90%      | ✅              | ❌              | 5%                      |
| **pUSD**        | 85%     | 90%      | ❌              | ✅              | 5%                      |

| **nBASIS-pUSD** | **LTV** | **LLTV** | **Collateral** | **Borrowable** | **Liquidation Penalty** |
| --------------- | ------- | -------- | -------------- | -------------- | ----------------------- |
| **nBASIS**      | 89%     | 92%      | ✅              | ❌              | 5%                      |
| **pUSD**        | 89%     | 92%      | ❌              | ✅              | 5%                      |

| **nTBILL-pUSD** | **LTV** | **LLTV** | **Collateral** | **Borrowable** | **Liquidation Penalty** |
| --------------- | ------- | -------- | -------------- | -------------- | ----------------------- |
| **nTBILL**      | 40%     | 50%      | ✅              | ❌              | 5%                      |
| **pUSD**        | 40%     | 50%      | ❌              | ✅              | 5%                      |

| **nCREDIT-pUSD** | **LTV** | **LLTV** | **Collateral** | **Borrowable** | **Liquidation Penalty** |
| ---------------- | ------- | -------- | -------------- | -------------- | ----------------------- |
| **nCREDIT**      | 40%     | 50%      | ✅              | ❌              | 5%                      |
| **pUSD**         | 40%     | 50%      | ❌              | ✅              | 5%                      |

| **yUSD-pUSD** | **LTV** | **LLTV** | **Collateral** | **Borrowable** | **Liquidation Penalty** |
| ------------- | ------- | -------- | -------------- | -------------- | ----------------------- |
| **yUSD**      | 75%     | 80%      | ✅              | ❌              | 5%                      |
| **pUSD**      | 75%     | 80%      | ❌              | ✅              | 5%                      |


# $ULAB

$ULAB will be the native governance and utility token of the LayerBank ecosystem.\
It is designed to align users, liquidity providers, and partners under a unified incentive model.

***

### **Vision for $ULAB**

* **Governance:** $ULAB holders will shape the future of LayerBank — from parameter updates (LTVs, reward distribution) to protocol upgrades.
* **Incentives:** $ULAB will power LayerBank’s reward system, including supply/borrow incentives and staking yields.
* **Cross-Chain Presence:** $ULAB is planned as an omnichain token, ensuring seamless usability across all supported networks.

***

### **Status**

* **Launch:** $ULAB has **not yet been launched**.
* **Home Chain:** The deployment chain for $ULAB is **to be decided** and will be announced before TGE.
* **Tokenomics:** Details (emissions schedule, staking mechanics, ve-models) will be published closer to launch.

***

### **What to Expect Next**

* **TGE Details:** Token generation event date and distribution breakdown
* **Staking & Governance:** How $ULAB will integrate with LayerBank’s staking and voting systems

> This page will be continuously updated as new information is finalized. Stay tuned for the official announcement of $ULAB’s launch and tokenomics.

***


# Locker

Users have the option to lock their $LAB tokens for a duration of up to 2 years. The longer they choose to lock their tokens and the greater the quantity of $LAB tokens they lock, the higher their xLAB balance becomes (xLAB is the locked version of the $LAB token).

$$
\rm xLAB= \frac{\rm My\~ lockup~~period}{\rm 2 year}\times  Locked~~LAB
$$

And depending on their xLAB score (xLAB stake), users can receive various benefits from the protocol's ecosystem. For example, Yield Boost (up to 3x), part of the platform fees, and $LAB staking rewards.

$$
\rm my~~Score = \frac{\rm my~~xLAB}{\rm total~~xLAB~~}
$$

These benefits incentivize users to participate in the locking mechanism and contribute to the protocol's stability and growth.

## $LAB Token utility:

{% tabs %}
{% tab title="Yield Boost" %}
The unique Yield Boosting System at LayerBank enhances user APR based on their xLAB stake rate(Score). The Boost multiplier increases as your Score, influenced by lockup duration and amount, rises, with a maximum boost of 3x.

$$
new~~a = min(3\times a~~, \~a+(1.5\times A \times{\rm my \~Score }))
$$

{% hint style="info" %}
$$a$$: This represents your total supplied or borrowed amount. For instance, if you supply 100 USDC to LayerBank, 'a' is 100.\
\
$$new\~a$$: This is the new amount increased by the APR booster. For example, if you receive a 2x boost multiplier, your 'new a' becomes 200 when supplying 100 USDC.\
\
$$A$$: This denotes the total supplied or borrowed amount within the protocol. For instance, if the total USDC supplied in the protocol is 1 million, 'A' is 1 million.
{% endhint %}

For example, if you supply 100 USDC to the protocol with a Score of 15%, and the total USDC supplied in the protocol is 1000, your 'new a' would become 300, and you receive a 3x boost multiplier. If your reward APR was initially 10%, it would increase to 30%.

However, it's important to note that as other users also lock up tLayerBank has a distinctive protocol revenue sharing system that distributes weekly protocol revenue in proportion to a user's Score (xLAB share). The sources of protocol revenue include:okens, and the total amount of locked $LAB tokens increases over time, your Score may decrease if you don't maintain constant lockups.
{% endtab %}

{% tab title="Share of Platform Fees " %}
LayerBank has a distinctive protocol revenue sharing system that distributes weekly protocol revenue in proportion to a user's Score (xLAB share).&#x20;

{% hint style="info" %}
**Protocol revenue sources:**

* Interest Fees : Revenue generated from interest fees on loans within the protocol.
* Liquidation Penalty : Revenue from penalties imposed during liquidations.
* **Fees for claiming platform revenue share**&#x20;
  {% endhint %}

Users can claim platform revenue share, but it can only be received in $LAB tokens. There is a 5% fee associated with claiming this share, and the fees collected are used to perform buybacks of $LAB tokens. This strategy is designed to significantly benefit the long-term value of the $LAB token.
{% endtab %}

{% tab title="Locking Rewards" %}
LAB token stakers receive $LAB staking (locking) rewards in proportion to their xLAB score.

If your xLAB score is 10%, and the weekly LAB reward allocation is 100,000, your share would be 10,000 LAB. This allocation ensures that stakers are rewarded according to their xLAB score, reflecting their contribution to the protocol.
{% endtab %}
{% endtabs %}


# Vest

The $LAB rewards obtained from lending and borrowing require a 90-day vesting period to claim in full.

<figure><img src="https://342097286-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fvi5sScuffF7lLX6pHEo5%2Fuploads%2FyI6NFSlTfDLDBKlhGjxu%2F%E1%84%89%E1%85%B3%E1%84%8F%E1%85%B3%E1%84%85%E1%85%B5%E1%86%AB%E1%84%89%E1%85%A3%E1%86%BA%202024-01-04%20%E1%84%8B%E1%85%A9%E1%84%92%E1%85%AE%204.36.39.png?alt=media&amp;token=f94aff62-06c7-4e72-b321-3eb8a1803785" alt=""><figcaption></figcaption></figure>

Here's how the vesting process works:

**Start Vesting**: Users can initiate the vesting process by choosing to start it. At this point, the LAB rewards accumulated in the pending rewards will begin to vest. Importantly, vesting does not affect the user's xLAB balance.&#x20;

<figure><img src="https://342097286-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fvi5sScuffF7lLX6pHEo5%2Fuploads%2FgvrppXbPeXcLmRVMD0Rt%2F%E1%84%89%E1%85%B3%E1%84%8F%E1%85%B3%E1%84%85%E1%85%B5%E1%86%AB%E1%84%89%E1%85%A3%E1%86%BA%202024-01-04%20%E1%84%8B%E1%85%A9%E1%84%92%E1%85%AE%204.56.20.png?alt=media&amp;token=ad51a2fc-a962-4d2e-9670-9c9b075a6f1f" alt=""><figcaption></figcaption></figure>

**Early Exit (Penalty Claim)**: During the vesting period, users have the option to exit early and claim their rewards. However, a penalty is applied based on the remaining vesting period, ranging from 10% to 90% of the original amount. LAB tokens collected as penalties are periodically burned.

**Completion of Vesting**: After the 90-day vesting period is completed, users can perform a withdrawal and receive 100% of the originally vested amount.

This vesting mechanism ensures that users receive their $LAB rewards over time, and it provides the flexibility to exit early with penalties if needed.


# Compound

<figure><img src="https://342097286-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fvi5sScuffF7lLX6pHEo5%2Fuploads%2FgQW9SqajWtJg5wS7jFVb%2Fimage.png?alt=media&amp;token=b6ffca9c-71e5-4602-b98f-f552af4b6ae1" alt=""><figcaption></figcaption></figure>

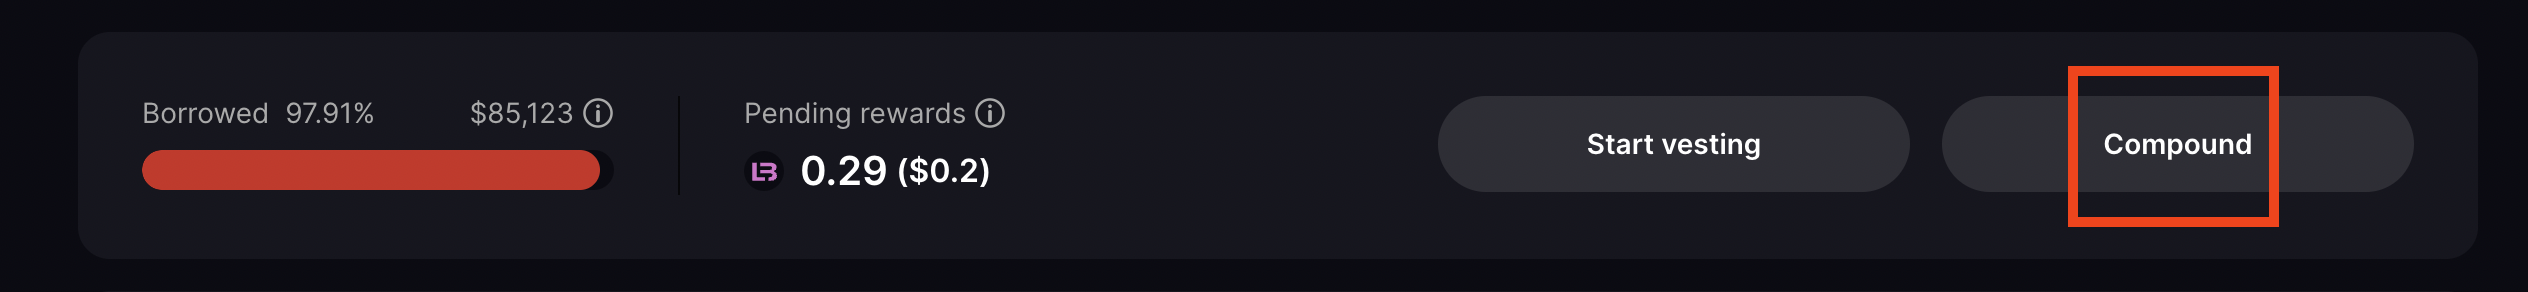
Compound is equivalent to directly locking the user's pending LAB rewards into the Locker without going through the vesting process. This allows for immediate locking and saves on gas fees. LAB tokens need to be vested for 90 days, so Compound starts with a minimum locking period of 90 days.


# $ULAB

**ULAB (Universal LayerBank Token)** is the governance and utility token of **LayerBank**, an omni-chain money market deployed across multiple networks.

ULAB is used to:

* Incentivize supply, borrow, and LP activity on LayerBank
* Lock into **ULAB LP** to obtain **xULAB** via the Locker
* Boost ULAB rewards and participate in governance

#### Token Summary

<table><thead><tr><th width="176.203125">Item</th><th>Value</th></tr></thead><tbody><tr><td>Name</td><td>Universal LayerBank Token</td></tr><tr><td>Symbol</td><td>ULAB</td></tr><tr><td>Total Supply</td><td>100,000,000 ULAB</td></tr><tr><td>Standard</td><td>ERC-20, Fungible Asset (Move), LayerZero OFT (cross-chain)</td></tr><tr><td>Contract</td><td>(TBA)</td></tr><tr><td>Chains</td><td>Movement, Base, and other LayerBank-supported networks</td></tr><tr><td>Role</td><td>Governance &#x26; utility token of the LayerBank protocol</td></tr></tbody></table>

#### Roles of ULAB

* **Reward Asset**\
  ULAB is distributed as incentives to suppliers, borrowers, and LP providers.
* **Locking & Boost Asset**\
  ULAB is paired into LP (e.g. ULAB–MOVE, ULAB–ETH) and locked in the **ULAB Locker** to mint **xULAB**, which boosts rewards.
* **Governance Primitive (WIP)**\
  xULAB is designed as the base primitive for future emission gauges and protocol governance.


# Tokenomics

### Overview

* **Token:** ULAB
* **Total Supply:** **100,000,000 ULAB**&#x20;
* **Design Goal:** Align long-term protocol growth, liquidity depth, and user incentives while minimizing short-term sell pressure.

ULAB is designed to function as the **core incentive and coordination token** of the LayerBank ecosystem, supporting liquidity, emissions, and future governance mechanisms.

<figure><img src="https://342097286-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fvi5sScuffF7lLX6pHEo5%2Fuploads%2F2L7UgxCkuFc43R7UURH9%2Fpie%20chart.png?alt=media&amp;token=91e0dc78-c4e1-4757-b80a-29e6ae130eb4" alt=""><figcaption></figcaption></figure>

***

### Token Allocation

<table data-full-width="true"><thead><tr><th>Category</th><th>Tokens</th><th>Allocation</th><th>TGE Unlock</th><th>Cliff (months)</th><th>Vesting (months)</th></tr></thead><tbody><tr><td>Core Team</td><td>15,000,000</td><td>15.0%</td><td>0%</td><td>6</td><td>24</td></tr><tr><td>Investors</td><td>15,000,000</td><td>15.0%</td><td>5%</td><td>3</td><td>13</td></tr><tr><td>Public Sale</td><td>1,000,000</td><td>1.0%</td><td>100%</td><td>–</td><td>–</td></tr><tr><td>Liquidity Provision</td><td>7,500,000</td><td>7.5%</td><td>100%</td><td>–</td><td>–</td></tr><tr><td>Liquidity Incentives</td><td>45,000,000</td><td>45.0%</td><td>10%</td><td>–</td><td>36</td></tr><tr><td>Airdrops</td><td>10,000,000</td><td>10.0%</td><td>100%</td><td>–</td><td>–</td></tr><tr><td>Strategic Reserves</td><td>6,500,000</td><td>6.5%</td><td>0%</td><td>3</td><td>24</td></tr><tr><td><strong>Total</strong></td><td><strong>100,000,000</strong></td><td><strong>100%</strong></td><td></td><td></td><td></td></tr></tbody></table>

***

### Allocation Rationale

<figure><img src="https://342097286-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fvi5sScuffF7lLX6pHEo5%2Fuploads%2FyW94TRzq4okAOR9tGefC%2Fgraph.png?alt=media&amp;token=5a82ec42-fd36-4d7f-8e91-8113f698bc35" alt=""><figcaption></figcaption></figure>

#### Core Team (15%)

* **TGE Unlock:** 0%
* **Cliff:** 6 months
* **Vesting:** 24 months
* Ensures long-term alignment and accountability for protocol development, security, and operations.

#### Investors (15%)

* **TGE Unlock:** 5%
* **Cliff:** 3 months
* **Vesting:** 13 months

#### Public Sale (1%)

* **TGE Unlock:** 100%

#### Liquidity Provision (7.5%)

* **TGE Unlock:** 100%
* Reserved for initial DEX liquidity and market bootstrapping at and after TGE.

#### Liquidity Incentives (45%)

* **TGE Unlock:** 10%
* **Vesting:** 36 months
* Primary incentive pool to support:
  * Long-term TVL growth
  * LP locking programs
  * xULAB-based reward boosting

#### Airdrops (10%)

* **TGE Unlock:** 100% unlocked at TGE, with flexible claim options
* Distributed to early users, contributors, and key ecosystem participants to drive broad distribution and strong network effects.

#### Strategic Reserves (6.5%)

* **TGE Unlock:** 0%
* **Cliff:** 3 months
* **Vesting:** 24 months
* Reserved for future partnerships, ecosystem initiatives, and strategic opportunities.


# Locker

The **ULAB Locker** is the module where users **lock ULAB LP** and receive **xULAB**.

Core ideas:

* You must lock ULAB LP in the Locker to obtain xULAB.
* Only users who lock enough ULAB LP vs. their Supply become Emission Eligible for ULAB rewards.
* xULAB is non-transferable and only comes from locked LP.

#### What Is Locked?

The Locker accepts **ULAB-based LP tokens**, such as:

* `ULAB–MOVE` LP
* `ULAB–ETH` LP
* `ULAB–Stables` LP

Additional ULAB LP pairs and chains can be added by the protocol / governance.

***

#### Reward Eligibility (Emission Eligibility)

ULAB rewards in each market are distributed **only** to users who satisfy an **Eligibility** condition.

Definitions (per market, Supply side):

* `SupplyValue` = total value (USD) you **supply** in that market
* `LockedLPValue` = total value (USD) of your **locked ULAB LP**

You are **Emission Eligible** in that market if:

$$
LockedLPValue≥0.03×SupplyValue
$$

Notes:

* **Borrow amounts are ignored** for eligibility (only Supply matters).
* Example:
  * If you supply **$1,000** in a market:
  * $$0.03×1,000=30$$

    → you must lock at least **$30** worth of ULAB LP to stay eligible.

If market or LP prices move and:

$$
LockedLPValue<0.03×SupplyValue
$$

then:

* You **lose Emission Eligible** status for that market.
* A **Kick** mechanism can be executed by protocol logic:
  * Marks your position as ineligible.
  * UI can notify you (e.g. “Not eligible for rewards — lock more ULAB LP”).

**2.2.1 Eligibility Summary**

<table><thead><tr><th width="196.08984375">Item</th><th>Description</th></tr></thead><tbody><tr><td>SupplyValue</td><td>Your supplied notional (USD) in the market</td></tr><tr><td>LockedLPValue</td><td>Your locked ULAB LP value (USD)</td></tr><tr><td>Eligibility condition</td><td>LockedLPValue ≥ 3% × SupplyValue</td></tr><tr><td>Below threshold</td><td>You can be kicked out of Emission Eligible status</td></tr><tr><td>Regain eligibility</td><td>Lock more ULAB LP or reduce SupplyValue</td></tr></tbody></table>

> If you are **not** Emission Eligible, you receive **0 ULAB** from that market, regardless of your xULAB, Score, or boost.


# xULAB

**xULAB** is a ve-style, non-transferable balance that you receive by **locking ULAB LP** in the Locker.

The amount of xULAB you get depends on:

* How much ULAB LP you lock (**LockedLPValue**)
* How long you lock it for (**LockPeriod**, up to 2 years)

#### Inputs

* `LockedLPValue`
  * Economic value (USD) of your locked ULAB LP.
* `LockPeriod`
  * Lock duration, chosen by the user, capped at **2 years** (24 months).

***

#### xULAB Formula

$$
\text{xULAB} = \Bigg( \min\Big(\frac{\text{Lock}\_{\text{Months}}}{24},\ 1\Big) \Bigg) \times \text{LockedLPValue}
$$

* Locking **longer** linearly increases your xULAB up to 24 months.
* Beyond 24 months, xULAB does **not** increase further (hard cap).

#### Example Table

Assume `LockedLPValue = $100`.

| Lock Period | Fraction of Max | xULAB Calculation | xULAB Result |
| ----------- | --------------- | ----------------- | ------------ |
| 3 months    | 3 / 24 = 0.125  | 0.125 × 100       | 12.5         |
| 12 months   | 12 / 24 = 0.5   | 0.5 × 100         | 50           |
| 24 months   | 24 / 24 = 1.0   | 1.0 × 100         | 100          |

***


# Score & Boost

This section covers:

* how xULAB becomes a **Score**, and
* how that Score determines your boosted effective amount `new_a` for rewards.

***

#### Score

Score represents your share of the total xULAB pool.

Definitions:

* $$\text{xULAB}\_i$$ : xULAB balance of user $$i$$
* $$∑\_j \text{xULAB}\_j$$ : total xULAB across all users

Score formula:

$$
\text{Score}\_i = \frac{\text{xULAB}\_i}{\sum\_j \text{xULAB}\_j}
$$

* Range: 0–1 (0%–100%)
* Interpretation: your percentage ownership of the Locker (xULAB system).

**Example**

* Your xULAB:  $$\text{xULAB}\_i = 50$$
* Total xULAB: $$∑j​xULABj​=5,000$$

$$
\text{Score}\_i = \frac{50}{5{,}000} = 0.01 = 1%
$$

Quick reference:

| Concept     | Description                          |
| ----------- | ------------------------------------ |
| xULABᵢ      | Your ve-style balance from locked LP |
| ΣxULAB      | Sum of xULAB from all users          |
| Scoreᵢ      | xULABᵢ ÷ ΣxULAB                      |
| High Scoreᵢ | Larger effect on boosts & flows      |

***

#### Boost Multiplier (new\_a)

The **Boost Multiplier** uses your Score to convert your raw position `a` into a boosted effective amount `new_a`.

This `new_a` is used to split ULAB emissions in that market.

Per market:

* $$a$$ : your liquidity in that market (USD)
  * e.g. your Supply amount
* $$A$$ : total liquidity of that market (USD)
  * sum of all users’ liquidity
* $$\text{Score}$$ : your Score from above

Boost formula:

$$
\text{new\_a} = \min\Big( 3 \times a,;; a + (1.5 \times A \times \text{Score}) \Big)
$$

* `a` = your original position
* `1.5 × A × Score` = bonus amount from your share of the system and total market size
* `3 × a` = hard cap (max 3× boost)

**Example**

Let:

* &#x20;$$a = 1{,}000$$
* $$A = 100{,}000$$
* &#x20;$$\text{Score} = 0.01$$ (1%)

1. Cap term:

$$
3 \times a = 3 \times 1{,}000 = 3{,}000
$$

2. Score term:

$$
a + (1.5 \times A \times \text{Score}) = 1{,}000 + (1.5 \times 100{,}000 \times 0.01) = 1{,}000 + 1{,}500 = 2{,}500
$$

3. Take minimum:

$$
\text{new\_a} = \min(3{,}000,; 2{,}500) = 2{,}500
$$

→ effective **2.5×** boost on your original `a`.

***

#### From new\_a to Rewards (Concept)

For each market:

* Total ULAB emissions for the epoch:

$$
\text{Emissions}\_{\text{market}}
$$

* Sum all users’ `new_a`:

$$
\sum\_j \text{new\_a}\_j
$$

* User $$i$$’s reward:

$$
\text{Reward}*i = \text{Emissions}*{\text{market}} \times \frac{\text{new\_a}\_i}{\sum\_j \text{new\_a}\_j}
$$

Chain of logic:

> Lock ULAB LP → xULAB → Score → new\_a → share of ULAB emissions

If you are not Emission Eligible (LockedLPValue < 3% × SupplyValue for that market), your effective reward is **0**, regardless of Score or `new_a`.


# Claim & Vesting

This section describes how ULAB rewards are claimed, vested, and optionally re-routed back into the Locker via **Compound** and **Instant Lock**.

***

#### Claim & Vesting

When you press **Claim (Start Vesting)**, the claimed ULAB starts a **90-day vesting** schedule.

Let:

* $$R$$ = total reward amount in this vesting batch
* $$d$$ = days elapsed since vesting started (0 ≤ d ≤ 90)

Claimable amount:

$$
\text{Claimable}(d) = R \times \Big(0.01 + 0.99 \times \frac{d}{90}\Big)
$$

Penalty amount:

$$
\text{Penalty}(d) = R \times \Big( 1 - \big(0.01 + 0.99 \times \frac{d}{90} \big) \Big)
$$

* Day 0:
  * Claimable = 1% of R
  * Penalty = 99% of R
* Day 45:
  * Claimable ≈ 50.5% of R
  * Penalty ≈ 49.5% of R
* Day 90:
  * Claimable = 100% of R
  * Penalty = 0

Each **Start Vesting** action creates a separate, independent 90-day stream.

***

#### Compound (Pre-Vesting)

**Compound** uses rewards that are **not yet vesting** (Pending ULAB) and sends them directly into the Locker as LP.

* Source: **Pending ULAB (before Start Vesting)**

Flow:

1. Select the amount of Pending ULAB.
2. Use Borrow/Zap/Wallet funds to create ULAB LP.
3. Choose lock duration (minimum 90 days up to 2 years).
4. Lock LP → receive xULAB.

This effectively converts short-term rewards into long-term locked liquidity and more xULAB, instead of liquid ULAB.

***

#### Instant Lock (In-Vesting)

**Instant Lock** uses rewards that are **already vesting**.

* Source: **Vesting ULAB (after Start Vesting)**

Flow:

1. Select a portion of vesting ULAB.
2. Use Borrow/Zap/Wallet funds to create ULAB LP.
3. Choose lock duration (minimum 90 days up to 2 years).
4. Lock LP → receive xULAB.

Both **Compound** and **Instant Lock** share the same “Create LP & Lock” UX; they differ only in where the ULAB comes from.

Comparison:

| Mode         | ULAB Source  | Vesting State   | Result                     |
| ------------ | ------------ | --------------- | -------------------------- |
| Compound     | Pending ULAB | Not vesting     | LP + xULAB (no vest)       |
| Instant Lock | Vesting ULAB | Already vesting | LP + xULAB (converts vest) |


# Governance (TBA)

(TBA)


# Disclaimer & Risk Disclosure

Users should exercise caution when interacting with any smart contract or blockchain application.\
While LayerBank conducts audits, testing, and bug bounty programs to mitigate risks, vulnerabilities in smart contract code may still exist.

***

### **Protocol Risks**

LayerBank is a decentralized, permissionless money market that allows users to **supply, borrow, and stake** assets across multiple EVM chains (Linea, Rootstock, Mode, Scroll, and more).

When interacting with LayerBank, users should be aware of the following risks:

* **Smart Contract Risk:** Undiscovered vulnerabilities may lead to partial or total loss of funds.
* **Market Risk:** Collateral values may fluctuate, potentially resulting in liquidation.
* **Shortfall Events:** Certain assets may be subject to slashing or protocol-wide loss allocation in extreme events.
* **Governance Risk:** DAO parameter changes (LTV, interest rate curves, reward emissions) may affect user positions.

Before using LayerBank, read the documentation and fully understand how the protocol works.

***

### **No Financial Advice**

Information on LayerBank’s website and documentation is provided **for informational purposes only** and does not constitute:

* Investment advice
* Financial advice
* Trading advice
* Any other form of professional advice

Users are responsible for their own due diligence and decisions.

***

### **APY Guidance**

All APYs displayed are **estimates** and for guidance purposes only.\
LayerBank operates across multiple chains and markets where available liquidity, utilization, and rewards fluctuate continuously.

* **APYs are not real-time guarantees.**
* **Past performance is not indicative of future results.**

***

### **Usage Risks**

LayerBank will not be responsible for losses, damages, or claims arising from (but not limited to):

* User errors (e.g. sending assets to the wrong address)
* Software issues (e.g. malware, unsafe libraries, wallet bugs)
* Technical failures (e.g. hardware wallet malfunction)
* Unauthorized access to user wallets
* Third-party risks (e.g. oracle failures, bridge exploits, counterparty defaults)

***

### **Investment Risks**

Cryptocurrency and DeFi participation can result in:

* Loss of principal
* High price volatility
* Impermanent loss (when providing liquidity)

Users are solely responsible for evaluating risks and determining whether to participate.

***

### **Tax Compliance**

Users are solely responsible for determining and complying with any tax obligations resulting from their activities on LayerBank.

***

### **No Warranties**

LayerBank is provided on an **“as-is”** and **“as-available”** basis.\
There are no warranties of any kind regarding LayerBank’s uptime, security, or functionality.\
Services may be disabled partially or entirely without prior notice.

***

### **Security**

Audits and monitoring programs reduce but do not eliminate risk.\
LayerBank cannot guarantee the protocol is completely secure or free from bugs, viruses, or potential exploits.

***

### **Limitation of Liability**

Unless required by law, LayerBank contributors, developers, and governance participants are **not liable** for any damages, including (but not limited to):

* Loss of use
* Loss of profits
* Loss of data or digital assets

arising from the use of LayerBank.

***

### **Arbitration**

By using LayerBank, you agree to arbitrate any dispute arising from or connected to LayerBank or this disclaimer, excluding disputes related to intellectual property (copyrights, logos, trademarks, trade names, trade secrets, or patents).


# L.Points

## **LayerBank Points (L.Points)**

LayerBank’s **L.Points Program** rewards active users and shares the upside from new chain integrations and potential airdrops.

Earn points by supplying, borrowing, and staking $ULAB — and convert your participation into real rewards.

***

### **How to Earn L.Points**

Points are calculated across **all supported chains and aggregated into a single global balance**.\
This means your activity on multiple chains contributes to one unified L.Points total.

| Action          | Rate (per $1)    | Notes                                            |
| --------------- | ---------------- | ------------------------------------------------ |
| **Supply**      | **0.3 L.Point**  | Earn points for providing liquidity.             |
| **Borrow**      | **2.4 L.Points** | Higher weighting for borrowing activity.         |
| **Stake $ULAB** | Coming Soon      | Staking will also earn points in future updates. |

***

### **Updates & Leaderboard**

* **Point Updates:** Every 6 hours
* **Leaderboard Refresh:** Every 24 hours
* **Where to Check:** Go to **L.Points** tab in the LayerBank app

***

### **Airdrop Disclaimer**

While L.Points are designed to share potential airdrops from chain partners, **LayerBank cannot guarantee airdrops on every chain**.\
Accumulating points simply increases your share if rewards are distributed.


# Audit report

LayerBank prioritizes security and transparency.\
All core smart contracts have undergone multiple independent audits by industry-leading security firms.

### **V1 Audit**

* **Auditor:** PeckShield
* **Scope:** Initial LayerBank V1 Lending Market (Linea)
* **Report:** [PeckShield Audit Report – LineaBank v1.0](https://github.com/peckshield/publications/blob/master/audit_reports/PeckShield-Audit-Report-LineaBank-v1.0.pdf)

***

### **V2 Audit**

* **Auditor:** PeckShield
* **Scope:** LayerBank V2 Upgrade (Multi-Chain Lending Market)
* **Report:** [PeckShield Audit Report – LayerBank v2.0](https://github.com/peckshield/publications/blob/master/audit_reports/PeckShield-Audit-Report-LayerBank-v1.0.pdf)

***

### **Move Audit**

* **Auditor:** MoveBit
* **Scope:** LayerBank Move Implementation (Movement & MoveVM Chains)
* **Report:** [MoveBit Final Audit Report – 2025.01.23](https://movebit.xyz/reports/20250123-LayerBank-Final-Audit-Report.pdf)

***

### **Leverage Vault (v3)**

* **Auditor:** AstraSec
* **Scope:** Automated Leverage Looping Vaults & E-Mode Enhancements
* **Report:** [AuditReport-LayerBank-V3](https://files.gitbook.com/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fvi5sScuffF7lLX6pHEo5%2Fuploads%2FgSR9vUclew9CtwxZGIL4%2FAstraSec-AuditReport-Layerbank-V3%20\(1\).pdf?alt=media\&token=905237fa-818d-4504-8c53-676615a9359e)

{% file src="/files/qfCWcuwUEwQcCf72LeOk" %}


# Github

{% embed url="<https://github.com/layerbank/contracts>" %}


# Official Links

Stay connected with LayerBank across all platforms:

* **Website:** [layerbank.finance](https://layerbank.finance/)&#x20;
* **𝕏 (Twitter):** [@LayerBankFi](https://twitter.com/LayerBankFi)&#x20;
* **Mirror:** [LayerBank Mirror](https://mirror.xyz/0x9f55e251abe51CbFadd06Ca0f4E5DCA0d0CeC20E)&#x20;
* **Discord:** [Join the Community](https://discord.gg/RUJPcP5uNr)&#x20;


# Media Kit

{% tabs %}
{% tab title="Assets" %}

<figure><img src="https://342097286-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fvi5sScuffF7lLX6pHEo5%2Fuploads%2FDQzvwRa67OxxOiFVMOkk%2Fmedia%20kit.png?alt=media&amp;token=1aa77b48-95a2-41b8-b9eb-f0ab992bd353" alt=""><figcaption></figcaption></figure>

{% file src="/files/t7kuzK51Fs7gUwOFIhgm" %}
{% endtab %}
{% endtabs %}


